Choosing health insurance after turning 65 can feel overwhelming. There are different plans, unfamiliar terms, monthly premiums, deductibles, and rules about which doctors you can visit. One option that attracts considerable attention is Medicare Advantage.
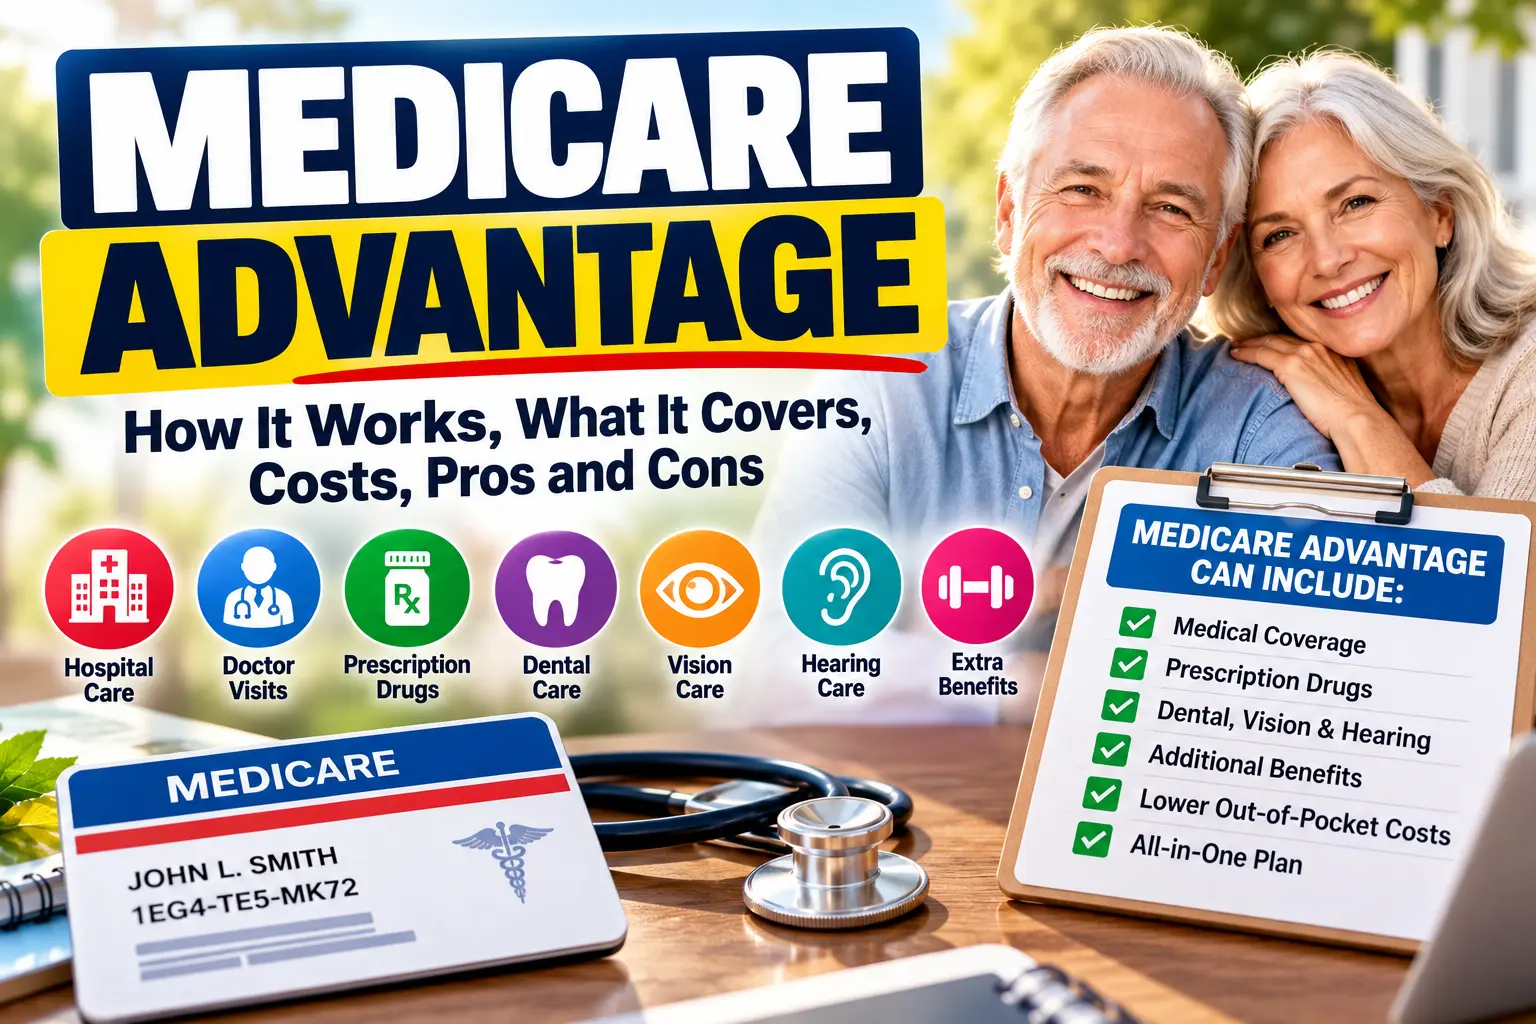
Medicare Advantage offers an alternative way to receive Medicare benefits through private insurance companies approved by the federal government. Many plans combine hospital coverage, medical services, and prescription drug coverage. Some also include additional benefits, such as routine dental care, vision exams, hearing services, and fitness programs.
At first glance, these plans can look like an easy way to get more coverage for less money. However, the right choice depends on more than a low monthly premium or a long list of extra benefits. Your doctors, prescriptions, expected medical expenses, travel habits, and preferred level of flexibility all matter.
This guide explains what Medicare Advantage is, how it works, what it covers, how much it costs, and what you should consider before enrolling.
What Is Medicare Advantage?
Medicare Advantage, also known as Medicare Part C, is a type of health insurance offered by private companies that have contracts with Medicare. Instead of receiving your Medicare Part A and Part B benefits directly through Original Medicare, you receive most of those benefits through the Medicare Advantage plan you select.
Medicare Part A generally covers inpatient hospital care, skilled nursing facility care under qualifying circumstances, hospice care, and certain home health services. Medicare Part B generally covers doctors’ services, outpatient care, preventive services, medical equipment, and other medically necessary services.
Medicare Advantage plans must cover the medically necessary services covered by Original Medicare, subject to Medicare’s applicable coverage rules. However, the plans can use different networks, cost-sharing arrangements, and approval requirements.
Most Medicare Advantage plans also include Medicare Part D prescription drug coverage. Depending on the plan, members may receive additional benefits that Original Medicare generally does not cover, such as certain dental, vision, and hearing services.
One important detail is that Medicare Advantage does not eliminate Medicare. You must generally have both Medicare Part A and Part B to enroll, and you must continue paying your Part B premium unless a qualifying program or plan benefit pays some or all of that amount.
In simple terms, Medicare Advantage combines your main Medicare-covered medical benefits into a plan administered by a private insurer.
How Does Medicare Advantage Work?
When you enroll in a Medicare Advantage plan, Medicare pays the insurance company to provide your covered Medicare benefits. You then use the plan’s membership card and follow its rules when receiving medical care.
The exact process depends on the type of plan.
For example, imagine you visit your primary care doctor for a routine appointment. You may pay a fixed copayment, such as an amount specified in your plan documents. If your doctor recommends a specialist, you may need a referral, depending on your plan. If you need a scan, surgery, or another service, the plan may require prior authorization before it agrees to cover the treatment.
These rules can affect both your expenses and how easily you can access care.
Medicare Advantage plans also have an annual maximum out-of-pocket limit for covered Medicare Part A and Part B services. Once you reach the applicable limit, the plan pays 100% of covered services for the remainder of that calendar year. Premiums and services that are not covered generally do not count toward this limit.
The limit is an important financial protection, but it does not mean every medical expense is capped. You should still review prescription drug expenses, noncovered services, and any other costs that may fall outside the limit.
Another important point is that Medicare Advantage plans are local. A plan available in one county may not be available in another, and benefits can differ significantly even when two plans carry the same insurance company name.
What Does Medicare Advantage Cover?
Medicare Advantage plans must cover Medicare-covered services under Part A and Part B, subject to applicable Medicare coverage requirements. Many plans also provide additional benefits.
1. Hospital Care
Medicare Advantage covers Medicare-covered inpatient hospital services. Depending on your plan, you may pay a copayment or coinsurance for hospital stays.
Before choosing a plan, examine its hospital cost-sharing rules carefully. A small difference in daily hospital charges can become significant if you need an extended stay.
You should also check whether the hospitals you prefer are included in the plan’s network.
2. Doctor Visits and Outpatient Care
Plans cover Medicare-covered medical services, including eligible primary care appointments, specialist visits, outpatient procedures, and other medically necessary care.
Your costs may differ depending on the service and whether you visit an in-network provider.
If you regularly see several specialists, check each doctor’s participation in the exact plan you are considering. An insurance company may offer multiple plans with different provider networks.
3. Prescription Drugs
Most Medicare Advantage plans include prescription drug coverage, often called an MA-PD plan.
However, prescription coverage is not identical across all plans. Each plan has its own formulary, which is the list of covered medications. Drugs may also have different cost-sharing requirements, restrictions, or preferred pharmacy arrangements.
Before enrolling, confirm that your current medications are covered and calculate their expected costs throughout the year.
A plan with an attractive medical benefit package may still be a poor choice if your prescriptions are expensive or difficult to obtain through its pharmacy network.
4. Dental Benefits
Some plans include benefits for services such as routine dental examinations, cleanings, X-rays, and certain other dental procedures.
The details matter. A plan that advertises dental coverage may have an annual allowance, a provider network, service-specific limits, or restrictions on major procedures.
Do not assume that every dental service is fully covered simply because the plan includes a dental benefit.
5. Vision and Hearing Services
Some Medicare Advantage plans cover routine eye examinations, eyeglasses or contact lenses within specified limits, hearing examinations, or hearing aids.
Coverage amounts, approved products, and participating providers vary.
If vision or hearing care is a priority, compare the actual allowance and the services included rather than relying on the headline benefit.
6. Fitness and Other Extra Benefits
Depending on the plan, additional benefits may include fitness programs, over-the-counter health product allowances, transportation for eligible medical visits, or meal support in certain circumstances.
Availability is not guaranteed, and eligibility rules may apply.
These benefits can be useful, but they should come after the basics: doctors, hospitals, prescription coverage, and total expected costs.
Types of Medicare Advantage Plans
Understanding the different plan types can help you decide which structure fits your needs.
Health Maintenance Organization (HMO)
HMO plans generally require you to use doctors and hospitals within their network for routine, nonemergency care. Many require members to select a primary care doctor, and referrals may be necessary to see certain specialists.
HMO plans can have relatively low premiums and predictable copayments. The trade-off is that you may have fewer choices when seeking care outside the network.
An HMO may suit someone whose preferred doctors and hospitals already participate in the plan and who is comfortable coordinating care through its network.
Preferred Provider Organization (PPO)
PPO plans generally provide more flexibility than HMO plans. Members can usually visit in-network providers at lower cost and may receive coverage for certain services from out-of-network providers at a higher cost.
You should not assume that every out-of-network doctor will accept the plan or that every service will be covered. Review the plan’s terms, especially for planned treatment and hospital care.
PPO plans may appeal to people who want more provider flexibility, but their premiums and out-of-network costs may be higher.
Special Needs Plans (SNPs)
Special Needs Plans are designed for people who meet specific eligibility requirements.
There are three main categories:
- Chronic Condition SNPs (C-SNPs): For eligible people with certain chronic conditions.
- Dual Eligible SNPs (D-SNPs): For people who qualify for both Medicare and Medicaid.
- Institutional SNPs (I-SNPs): For eligible people who need, or are expected to need, the level of care associated with certain institutions or long-term care arrangements.
SNPs tailor their benefits, provider networks, and care coordination to the populations they serve. Eligibility requirements vary by plan.
Private Fee-for-Service Plans
Private Fee-for-Service plans establish payment terms for covered services. Depending on the plan, providers must meet specific requirements and agree to the plan’s payment terms.
Before receiving care, confirm that the provider accepts the plan’s conditions. Provider participation may be less straightforward than with a conventional network-based plan.
Medical Savings Account Plans
Medicare Medical Savings Account plans combine a high-deductible Medicare Advantage plan with a medical savings account funded by the plan.
The account can help pay eligible medical expenses, while the insurance coverage applies according to the plan’s deductible and other rules. These plans have specific features and eligibility considerations, and they generally do not include Part D prescription drug coverage.
They may appeal to some people who want to manage a portion of their healthcare spending themselves, but they require careful consideration of the deductible and account arrangements.
How Much Does Medicare Advantage Cost?
There is no single price for Medicare Advantage. Your costs depend on the plan, location, benefits, and medical services you use.
A useful way to compare plans is to examine the following expenses together.
Monthly Premium
Some Medicare Advantage plans advertise a $0 monthly plan premium. This means the plan does not charge an additional premium for the plan itself.
It does not mean all healthcare is free.
Most people enrolled in Medicare Advantage must continue paying their Medicare Part B premium. You may also face deductibles, copayments, coinsurance, and other expenses when receiving care.
In 2026, the standard Medicare Part B premium is $202.90 per month, although some people pay a different amount based on income or other applicable circumstances.
Plan premiums and benefits can change from year to year, so verify the figures that apply to your coverage period.
Deductible
A deductible is the amount you must pay for certain covered services before the plan begins paying according to its benefit structure.
Some plans have no medical deductible, while others apply deductibles to particular services or prescription coverage.
Check whether the deductible applies to medical care, medications, or both.
Copayments and Coinsurance
A copayment is a fixed amount you pay for a covered service. Coinsurance is a percentage of the allowed cost that you are responsible for paying.
For example, a plan might charge one amount for a primary care visit and a different amount for specialist care. Hospital stays, outpatient procedures, and diagnostic services may have separate cost-sharing rules.
These expenses can add up, especially if you need frequent appointments or ongoing treatment.
Maximum Out-of-Pocket Limit
Medicare Advantage plans must establish an annual limit for covered Medicare Part A and Part B services.
Once you reach the applicable limit, you generally pay nothing for those covered services for the rest of the calendar year.
This protection is one of the major financial differences between Medicare Advantage and Original Medicare without supplemental coverage. Original Medicare does not have a general annual out-of-pocket maximum for Part A and Part B services.
However, the plan’s limit does not automatically include every healthcare-related expense. Premiums, most prescription drug costs, and services that are not covered are treated separately under the applicable rules.
Prescription Drug Costs
Prescription costs can vary according to the medication, formulary tier, pharmacy, deductible, and other plan provisions.
If you take several medications, estimate your annual prescription spending instead of comparing premiums alone.
A plan with a lower monthly premium may cost more overall if your medicines have higher copayments or less favorable coverage.
A Simple Cost Comparison
Suppose you are comparing two plans.
Plan A has a $0 additional monthly premium but higher copayments for specialist visits. Plan B charges an additional monthly premium but offers lower cost-sharing for the specialists you visit regularly.
If you rarely need medical care, Plan A might cost less. If you have several specialist appointments throughout the year, Plan B could offer better overall value.
The correct answer depends on your actual healthcare needs. Comparing expected annual spending is more useful than choosing the plan with the lowest advertised premium.
Advantages of Medicare Advantage
Medicare Advantage can be a practical option for people who want their Medicare benefits administered through one private plan.
1. Additional Benefits
Many plans offer benefits beyond Original Medicare, including certain dental, vision, and hearing services. Depending on your needs, these benefits may reduce the amount you pay for routine care.
2. Annual Out-of-Pocket Protection
The annual limit on covered Part A and Part B services helps protect members from unlimited cost-sharing for those services during a calendar year.
This can make healthcare spending more predictable, although your actual costs depend on the plan and services used.
3. Potentially Low Additional Premiums
Some plans charge no additional monthly premium beyond the Part B premium. This can make them attractive to people managing a limited retirement budget.
However, a low premium should always be evaluated alongside deductibles, copayments, prescription costs, and provider access.
4. Combined Medical and Drug Coverage
Many Medicare Advantage plans include prescription drug coverage, allowing members to manage medical and drug benefits through a single plan.
This can simplify administration compared with maintaining separate medical and drug policies.
5. Coordinated Care
Some plans provide care coordination, provider networks, and support for managing chronic conditions.
For people who prefer a more structured approach to healthcare, this organization can be useful.
Disadvantages of Medicare Advantage
Although Medicare Advantage has potential benefits, it also has limitations that deserve serious attention.
1. Provider Networks Can Restrict Your Choices
HMO plans generally require network providers for routine care, while PPO plans may cover some out-of-network services at higher cost.
If your preferred doctor leaves the network or a specialist you need does not participate, you may have to change providers or pay more.
This is particularly important if you have a long-standing relationship with a specialist or receive treatment from a particular hospital.
2. Prior Authorization May Be Required
Some Medicare Advantage plans require prior authorization before covering certain treatments, procedures, equipment, or services.
Prior authorization means the plan reviews a request before approving coverage. This process can help manage medical spending, but it can also create paperwork, delays, or disputes.
Ask which services require authorization and what happens if a request is denied.
3. Costs Can Be Difficult to Predict
A $0 premium does not mean $0 healthcare costs. Frequent specialist visits, hospital care, outpatient procedures, and prescription medications can create substantial expenses.
Reviewing the plan’s maximum out-of-pocket limit and service-specific copayments helps you understand the financial risk.
4. Extra Benefits May Have Restrictions
Dental, vision, hearing, transportation, and other supplemental benefits may have annual limits, provider restrictions, or eligibility conditions.
Read the benefit details carefully before assigning a dollar value to these extras.
5. Coverage May Be Less Convenient When Traveling
Some plans offer limited routine out-of-network coverage. If you spend several months in another state, travel frequently, or maintain homes in different locations, this could become an issue.
Emergency and urgently needed care generally receive special treatment under Medicare Advantage rules, but routine care away from home may be more complicated.
Check the plan’s travel and out-of-area coverage before enrolling.
6. Switching Plans Requires Planning
You cannot change Medicare Advantage plans whenever you want. You must generally use a valid enrollment period or qualify for a special enrollment opportunity.
Before switching, understand how the change affects your doctors, medications, benefits, and other insurance.
Medicare Advantage vs. Original Medicare
One of the most important decisions is whether to receive Medicare benefits through Medicare Advantage or Original Medicare.
Original Medicare is the traditional federal program consisting of Part A and Part B. You can generally see any doctor or hospital nationwide that accepts Medicare, subject to applicable rules.
Medicare Advantage uses private plans with their own benefit structures and provider arrangements.
With Original Medicare, you can usually add a separate Part D plan for prescription drugs. You may also be able to purchase a Medicare Supplement Insurance policy, known as Medigap, to help cover certain out-of-pocket expenses. Medigap generally cannot be used to pay Medicare Advantage cost-sharing.
Medicare Advantage plans often include prescription drug coverage and may provide additional benefits, but provider networks and prior authorization can affect access to care.
Neither option is automatically better for everyone.
Original Medicare may appeal to someone who prioritizes broad access to providers that accept Medicare and wants the option of Medigap. Medicare Advantage may appeal to someone who prefers a managed plan, values included extra benefits, and is comfortable using its network.
Your budget, health needs, location, and eligibility for other assistance should guide the decision.
Who Should Consider Medicare Advantage?
Medicare Advantage may be worth considering if you:
- Prefer managing your main Medicare benefits through one plan.
- Have confirmed that your doctors and hospitals participate.
- Want to compare plans that include prescription drug coverage.
- Value available dental, vision, or hearing benefits.
- Understand the plan’s cost-sharing and authorization requirements.
- Are comfortable with the plan’s provider network and service area.
It may be less suitable if you need regular access to providers outside the network, travel frequently for routine medical care, or strongly prefer the flexibility of Original Medicare.
People with complex medical needs should review their current doctors, hospitals, prescriptions, and likely treatments before making a decision.
If you qualify for Medicaid or receive help with Medicare costs, investigate plans designed for people with your eligibility status. The best option may differ from the one that works for someone without that assistance.
How to Choose the Right Medicare Advantage Plan
Choosing a plan should involve more than looking at advertisements. Use the following steps to make a more informed decision.
Step 1: List Your Current Doctors
Write down your primary care physician, specialists, preferred hospitals, and other important providers.
Check each one against the exact plan you are considering. Do not assume that participation in one plan means participation in every plan offered by the same insurer.
Step 2: Review Your Prescriptions
List every medication you take, including the dosage and frequency.
Check the plan’s formulary, pharmacy requirements, restrictions, and expected costs. If you take expensive medications, this step can make a major difference in your annual spending.
Step 3: Calculate Your Expected Annual Costs
Add the premiums, likely copayments, deductibles, and expected prescription expenses.
Then consider a year in which you need more care than usual. Review the plan’s maximum out-of-pocket limit for covered medical services and determine whether the potential financial exposure is manageable.
No calculation can predict every medical event, but comparing realistic scenarios can reveal differences that monthly premiums hide.
Step 4: Compare Additional Benefits
Look at dental, vision, hearing, fitness, transportation, and other supplemental benefits.
Confirm the dollar limits, eligible services, provider networks, and any conditions for using them. A benefit only has meaningful value if it covers something you need and can actually access.
Step 5: Understand Referrals and Prior Authorization
Determine whether you need referrals to see specialists and which services require prior authorization.
If you have an upcoming procedure or ongoing treatment, ask how the plan handles that type of care.
Step 6: Consider Travel and Future Needs
Think about where you spend your time, whether you travel regularly, and whether you may need specialized treatment in the future.
A plan that fits your life today should also make sense for your likely healthcare needs over the next year.
Step 7: Compare the Full Plan Documents
Read the plan’s Summary of Benefits and Evidence of Coverage. These documents explain covered services, cost-sharing, limitations, and other important rules.
If something is unclear, contact the insurer and request an explanation. Keep a record of the information you receive.
When Can You Enroll in Medicare Advantage?
Enrollment timing is important because you generally cannot join or switch plans at any time of the year.
Initial Enrollment Period
When you first become eligible for Medicare, you have an Initial Enrollment Period associated with your eligibility. For most people turning 65, it spans seven months: the three months before their birthday month, their birthday month, and the three months afterward.
The precise rules and effective dates can vary depending on your circumstances. If you are delaying Medicare because you have employer coverage, check how that coverage affects your enrollment responsibilities.
Annual Medicare Open Enrollment
The annual Medicare Open Enrollment Period runs from October 15 through December 7.
During this period, eligible beneficiaries can generally join, switch, or drop Medicare Advantage plans, change between Original Medicare and Medicare Advantage, and make certain prescription drug coverage changes.
Changes made during this period generally take effect on January 1 of the following year.
This is an opportunity to review your coverage rather than automatically renew your current plan without checking its new terms.
Medicare Advantage Open Enrollment Period
The Medicare Advantage Open Enrollment Period runs from January 1 through March 31 for people who are already enrolled in a Medicare Advantage plan.
During this period, eligible beneficiaries can generally switch to another Medicare Advantage plan or return to Original Medicare. If they return to Original Medicare, they can also join a standalone Part D plan.
This period is not a general opportunity for people enrolled in Original Medicare to join a Medicare Advantage plan.
Special Enrollment Periods
Certain life events can create a Special Enrollment Period. Examples may include moving outside your plan’s service area, losing qualifying coverage, or becoming eligible for certain assistance programs.
The rules and deadlines depend on the specific event, so check your eligibility before making a change.
Common Medicare Advantage Mistakes to Avoid
A few avoidable mistakes can make a plan more expensive or less useful than expected.
Choosing a plan based only on its premium. A $0 premium does not tell you how much you will pay when receiving care.
Assuming your doctor is covered. Verify network participation for the specific plan, not merely the insurance company’s name.
Ignoring prescription coverage. Check every medication, including any restrictions that could affect access or cost.
Overlooking the annual cost-sharing limit. Understand how much you could owe for covered medical services in a difficult healthcare year.
Believing every extra benefit is unlimited. Dental, vision, and other benefits often have specific terms and restrictions.
Waiting until the deadline to compare plans. Starting early gives you time to check providers, medications, and plan documents without rushing.
Ignoring next year’s changes. Premiums, benefits, networks, drug coverage, and cost-sharing can change. Review your coverage every year.
Frequently Asked Questions About Medicare Advantage
Is Medicare Advantage the same as Medicare?
No. Medicare Advantage is an alternative way to receive Medicare Part A and Part B benefits through a Medicare-approved private plan. Original Medicare is the traditional federal program. Medicare Advantage plans must follow Medicare requirements but can have different networks and cost-sharing rules.
Is Medicare Advantage free?
Not necessarily. Some plans have a $0 additional monthly premium, but members generally still pay the Medicare Part B premium and may have copayments, deductibles, coinsurance, and prescription costs.
Does Medicare Advantage cover prescription drugs?
Most Medicare Advantage plans include Part D prescription drug coverage. However, coverage varies by plan. Check the formulary and the costs of your specific medications before enrolling.
Can I keep my current doctor?
Possibly. It depends on whether your doctor participates in the plan and the plan’s rules. Confirm directly with both the doctor’s office and the insurance company before making a decision.
Can I switch from Medicare Advantage to Original Medicare?
Yes, but generally only during an applicable enrollment period or if you qualify for a Special Enrollment Period. Before switching, review how you will obtain prescription coverage and whether you can purchase Medigap under the rules that apply to your situation.
Does Medicare Advantage have an out-of-pocket maximum?
Yes. Medicare Advantage plans must set an annual maximum for covered Medicare Part A and Part B services. After you reach the applicable limit, the plan pays 100% of covered services for the remainder of the calendar year. Other expenses, such as premiums and certain noncovered services, may not count toward that limit.
Is Medicare Advantage better than Medigap?
They serve different purposes and are not interchangeable. Medicare Advantage replaces the way you receive most Part A and Part B benefits and generally uses plan-specific rules. Medigap supplements Original Medicare by helping pay certain out-of-pocket costs. You generally cannot use Medigap to pay Medicare Advantage cost-sharing.
Can I have Medicare Advantage and a separate Part D plan?
Most Medicare Advantage plans include prescription drug coverage. If you join a separate Part D plan while enrolled in a Medicare Advantage plan that includes drug coverage, you may be disenrolled from the Medicare Advantage plan, with limited exceptions. Check the rules before enrolling in separate coverage.
Does Medicare Advantage cover dental and vision?
Many plans offer some dental and vision benefits, but the amount and type of coverage vary. Check which services are included, the applicable limits, and whether you must use particular providers.
What should I check before enrolling?
Start with your doctors, hospitals, prescriptions, total expected annual costs, out-of-pocket limit, and coverage rules. Then compare supplemental benefits and make sure the plan suits your travel habits and healthcare needs.
Final Thoughts: Is Medicare Advantage Worth It?
Medicare Advantage can offer a useful combination of medical coverage, prescription drug benefits, and additional services. For some people, it provides an affordable way to organize their healthcare and manage covered medical expenses.
But the best plan is not necessarily the one with the lowest premium, the most extra benefits, or the most appealing advertisement. It is the plan that provides access to the care you need at a cost you can manage.
Before enrolling, check your doctors, prescriptions, hospitals, cost-sharing rules, and annual out-of-pocket limit. Compare the complete plan documents, consider how your healthcare needs might change, and review your options during the appropriate enrollment period.
Taking the time to compare these details can help you avoid unpleasant surprises and choose coverage that fits your health, budget, and lifestyle.